Languages
Friday, October 16, 2026


News and Views from the Global South
Financial Crisis

Alcoholism Cannot Explain Russian Mortality Spike
The steep upsurge in mortality and sudden fall in life expectancy in Russia in the early 1990s were the highest ever registered anywhere in recorded human history in the absence of catastrophes, such as wars, plague or famine. The shock economic reforms in the former Soviet economies after 1991 precipitated this unprecedented increase in mortality, shortening life expectancy, especially among middle-aged males.
The G20 Needs To Go Back to its Roots
When the finance ministers of the G7 countries proposed the G20 in the late 1990s, a good sense of realism prevailed. They recognized that addressing issues of global finance required the political support from—and involvement of—emerging market economies.
Prepare Now for the Next Financial Crisis
The Asian financial crisis started 20 years ago and the global financial crisis and recession 9 years back. When a new global financial crisis strikes, the developing countries will be more damaged than in the last crisis as they have become less resilient and more vulnerable. They thus need to prepare from being overwhelmed.
Early Death in Russia
The transition to market economy and democracy in the Russian Federation in the early 1990s dramatically increased mortality and shortened life expectancy. The steep upsurge in mortality and the decline in life expectancy in Russia are the largest ever recorded anywhere in peacetime in the absence of catastrophes such as war, plague or famine.
Reforming the International Financial System
When we fail to act on lessons from a crisis, we risk exposing ourselves to another one. The 1997-1998 East Asian crises provided major lessons for international financial reform. Two decades later, we appear not to have done much about them. The way the West first responded to the 2008 global financial crisis should have reminded us to do more. But besides accumulating more reserves, Southeast Asia has not done much else.
G20’s Record Does Not Inspire Hope
The G20 leaders meeting in Hamburg, Germany, on 7-8 July comes almost a decade after the grouping’s elevation to meeting at the heads of state/government level. Previously, the G20 had been an informal forum of finance ministers and central bank governors from advanced and emerging economies created in 1999 following the 1997-1998 Asian financial crisis.
1997 Asian Crisis Lessons Lost
After months of withstanding speculative attacks on its national currency, the Thai central bank let it ‘float’ on 2 July 1997, allowing its exchange rate to drop suddenly. Soon, currencies and stock markets throughout the region came under pressure as easily reversible short-term capital inflows took flight in herd-like fashion. By mid-July 1997, the currencies of Indonesia, Malaysia and the Philippines had also fallen precipitously after being floated, with stock market price indices following suit.
Southeast Asia: From Miracle To Debacle
The World Bank and other influential international financial institutions and development agencies have been touting Southeast Asian (SEA) newly industrializing countries as models for emulation, especially by African developing countries seeking to accelerate their development transformations. But these recommendations are usually based on misleading analysis of their rapid growth and structural transformation.
Putting the Spotlight on Women Migrant Workers
Migrant workers, and their economic contribution to the development of both the country of origin and the host country, have caught the eye of governments and policymakers worldwide.
UN Response Teams Underfunded as Costs Hit Staggering $23.5 Billion
UN response teams that help the most vulnerable people in the world are still largely underfunded, a new status report has revealed. The funding available to the teams is no match for the record number of people—141 million—who need assistance today.
East Asia’s Real Lessons
International recognition of East Asia’s rapid economic growth, structural change and industrialization grew from the 1980s. In Western media and academia, this was seen as a regional phenomenon, associated with some commonality, real or imagined, such as a supposed ‘yen bloc’.
UN Work Stoppage in Geneva Halts Human Rights Meeting
As UN staffers in Geneva threaten a strike, protesting a proposed salary cut of over 7.5 percent, a token two-hour “work stoppage” last week forced the Human Rights Council to suspend its meeting.
Migrant Workers Pour Trillions into World Economy
A new report by the International Fund for Agricultural Development (IFAD) says the flow of money from migrants—commonly located in developed countries—to their families in lower income countries has doubled over the last decade.
East Asian Miracle Myth Making
Even before the term ‘Washington Consensus’ (WC) was popularized, it was already coming under great criticism despite the ‘counter-revolutions’ against ‘development economics’ and Keynesian economics associated with Thatcherism and Reaganomics. At the World Bank, the Japanese Executive Director argued that the WC menu of policy advice and conditionalities had resulted in the 1980s’ ‘lost decade’ in Latin America and Africa. In contrast, the East Asian region had seen rapid growth and industrialization.
Post-Soviet Russian economic collapse
Wide-ranging economic reforms following the demise of the Soviet Union at the end of December 1991 mainly resulted in economic collapse in most successor states. By the mid-1990s, output had fallen by about half compared to 1989.
Global South Calls for International Body to Fight Tax Havens
Tax havens are “one of the worst enemies of our democracies,” said state representatives during a meeting at the United Nations.
Why Do International Financial Crises Happen?
International currency and financial crises have become more frequent since the 1990s, and with good reason. But the contributory factors are neither simple nor straightforward. Such financial crises have, in turn, contributed to more frequent economic difficulties for the economies affected, as evident following the 2008-2009 financial crisis and the ensuing Great Recession still evident almost a decade later.
Proposed UN Pay Cuts Threaten Work Stoppage in Geneva
Facing significant reductions in US financial contributions from a politically-unpredictable Donald Trump administration, the UN Secretariat is gearing itself for a rash of austerity measures and budgetary cuts, including downsizing peacekeeping operations and cuts in development aid, reproductive health and overseas travel.
Why the G7 Must Fund Health & Nutrition
The G7 Summit, held annually among the leaders of the world’s most powerful economies (Canada, France, Germany, Italy, Japan, the United Kingdom, the United States, and the EU), plays an important role in shaping responses to global challenges—theoretically at least.
Slow Growth Stalls SDGs’ Progress
The world will not be on track to eradicate poverty by 2030 if current growth trends continue, a UN task force found.
International Finance Governance Undemocratic
Why is it so difficult to achieve meaningful coordination when everybody agrees that it is desirable, if not necessary? President Richard Nixon’s withdrawal of the US from and hence termination of the Bretton Woods system in 1971 confirmed the end of the post-war Golden Age. This led to slower growth, greater volatility, more instability, and reduced progress in raising economic welfare, among other consequences.« Previous Page — Next Page »




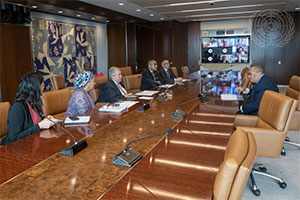 Secretary-General Meets with Members of Debt Expert Group. Credit: UN Photo/Eskinder Debeb
Financial crises are often defined by banking panics, recession, loss of market value, and deflation. Various financial crises at the turn of the 20th century, such as the Asian Crisis of 1997-1998 and the 2007-2008 Global Financial Crisis, have had immense impacts on the world economy. The COVID-19 pandemic also caused a financial crisis when mass lockdowns triggered staggering unemployment rates, a stagnation of economic growth, and led to the 2020 stock market crash. With the Russian invasion of Ukraine, the world has also witnessed a global energy crisis with shortages and increased prices in oil, gas, and electricity markets. According to UNCTAD’s World of Debt 2025, global public debt surpassed $100 trillion in 2024, with developing country debt growing twice as fast as developed economies since 2010. Burdens of debt servicing come with economic slowdowns and demands of austerity from lenders, with some economists arguing that this will lead to a new “lost decade” for the Global South. IPS brings you worldwide coverage of these financial developments and how we should manage these crises.

The Week with IPS

NEXT STOP - SDGs
Tracking global progress towards a sustainable world
Tracking global progress towards a sustainable world
