Languages
Tuesday, September 29, 2026


News and Views from the Global South
Financial Crisis

Share Buybacks Enable Predatory Value Extraction
‘Getting government out of the way’, the neoliberal ‘free market’ mantra, was supposed to boost private investment. Instead, business investment has declined as a consequence. Many economies now seem incapable of making much needed investments to sustain growth, apparently due to ‘capital allocation’ problems.
Global Economic Consequences of COVID-19
The panic resulting from the events starting with the deaths in Wuhan keeps spreading globally faster than the spreading of the virus itself. Quite apart from the immediate health dangers, now a new economic danger looms large globally. We are facing the prospects of a deep and lasting global recession regardless of the health policy and economic policy measures taken by China, the US and other countries unless there is timely global cooperation and coordination. What will be the global economic impact of COVID-19 if swift and effective action is not taken globally? Is there a way to find out through some kind of rigorous model-based economic analysis?
CORRECTED VERSION: Stock Market Bubble Threat
The US is currently still in a stock market bubble which, if history is any guide, is likely to end, as argued by Thomas Palley. While President Trump would, of course, like to sustain it to strengthen his November re-election prospects, the Covid19 black swan is already showing signs of pricking the bubble
Coronavirus Exposes Global Economic Vulnerability
As the outbreak of the novel coronavirus COVID-19 threatens a global pandemic, major stock markets around the world have suffered their worst performance since the 2008 financial crush.
Lucky Trump Looking Smug
Meeting the President of the Republic of Korea in September 2019, President Donald J Trump bragged that the “US economy is the envy of the world”. Trump reiterated such claims in his State of the Union address in early February, hailing his own policies with typical humility.
Global Economy Still Slowing, Dangerously Vulnerable
In an annual ritual early in the year, most major economic organizations have released forecasts for the global economy in 2020. Incredibly, almost as a reminder of where financial power resides in this day and age, the International Monetary Fund (IMF) released its forecasts at the World Economic Forum’s 50th annual meeting in Davos.
Intellectual Property Raises Costs of Living
Many medicines and medical tests are unaffordable to most of humanity owing to the ability of typically transnational pharmaceutical giants to abuse their monopoly powers, enforced by intellectual property laws, to set prices to maximize profits over the long-term.
Financialization Increases Inequality
Financialization has worsened inequality through various channels, including macroeconomic policies. For example, quantitative easing and low, if not negative interest rates have fuelled credit and asset price bubbles, while fiscal spending cuts have adversely affected those depending on government assistance.
Exchange Rate Undervaluation for Export-Led Growth Promotion
One mercantilist view is that exchange rate undervaluation – e.g., via accumulation of foreign exchange reserves in China’s case – is ‘industrial policy’ to promote export-led growth, benefiting producers of exports while discouraging imports.
Was China Manipulating Its Currency?
Many argue that China’s impressive growth for last four decades has been due to deliberate exchange rate undervaluation, promoting exports and discouraging imports. In August last year, the Trump administration accused China of engaging in currency manipulation.
Billionaires Beware
The latest November 2019 UBS/PwC Billionaires Report counted 2,101 billionaires globally, or 589 more than five years before. Earlier, Farhad Manjoo had seriously recommended, ‘Abolish Billionaires’, presenting a moral case against the super-rich as they have and get far, far more than what they might reasonably claim to deserve.
Reflections for a New Year
In a world shaken by so many problems, it is difficult to look at 2020 and not make some kind of holistic analysis. While enormous progress has been made on many fronts, it is clear that the tide has turned, and we are now entering – or have already entered – a new low point in the history of humankind..
Why Is Growth Slowing in China?
China’s gross domestic product (GDP) grew by 14%. Since then, its growth rate has declined by more than half to 6.6% in 2018. The five-year moving average growth rate is at its lowest since reforms began in 1978, although annual growth briefly fell lower during 1989, the year of the Tian An Men incident.
Inequality and Its Many Discontents
Much recent unrest, such as the ‘yellow-vest’ protests in France and the US ‘Abolish the Super-Rich’ campaign, is not against inequality per se, but reflects perceptions of changing inequalities. Most citizens resent inequalities when it is not only unacceptably high, but also rising.
Social Protection Necessary to Quickly End Poverty, Hunger
Historically, most social security systems have developed in the formal sector of rich economies. However, most of the poor and hungry in the world live in rural areas, surviving in the informal economy.
More Austerity for Developing Countries: It’s Bad News, and It’s Avoidable
After years of austerity, a number of Eurozone countries are now considering expansionary fiscal policies. And in the UK, government spending is set to return to levels last seen in the 1970s. But austerity abounds elsewhere in the world, including in some of the poorest countries.
A New Deal for Sustainable Development
Almost nine decades ago, newly elected US President Franklin Roosevelt introduced the New Deal in 1933 in response to the Great Depression. The New Deal consisted of a number of mutually supportive initiatives, of which the most prominent were: a public works programme financed by budget deficits; a new social contract to improve living standards for all working families, including creation of the US social security system; and financial regulation to protect citizens’ assets and channel financial resources into productive investments.
Trade Liberalization for Development?
The International Monetary Fund (IMF), the World Bank and the World Trade Organization (WTO), all dominated by rich countries, have long promoted trade liberalization as a ‘win-win’ solution for “all people—rich and poor—and all countries—developed and developing countries”, arguing that “the gains are large enough to enable compensation to be provided to the losers”.
Industrial Policy Still Relevant
Industrial policy refers to the promotion of new investments and technology by governments to encourage the growth and development of specific economic sectors. However, scepticism persists about the feasibility and desirability of using industrial policy, especially of the ability to ‘pick winners’, often accused of leading to ‘propping-up failing industries’.
Development Banks Needed to Finance Sustainable Development
Public or state development banking will be vital to achieving the Sustainable Development Goals, argues UNCTAD’s Trade and Development Report 2019 (TDR 2019). Ongoing World Bank led efforts seek to leverage private finance via shadow banking by using public money to guarantee handsome returns managed by giant investment houses. Such financialization introduce new costs and risks to financing investments for sustainable development, decent work and renewable energy.
Africa’s Investment Drive Gathers Pace
Headwinds are blowing amid IMF warnings of a “synchronised slowdown” in global economic growth, yet Africa’s investment drive is still gathering pace, supported by intense international competition in development finance.« Previous Page — Next Page »


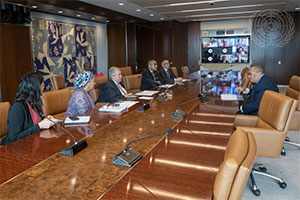 Secretary-General Meets with Members of Debt Expert Group. Credit: UN Photo/Eskinder Debeb
Financial crises are often defined by banking panics, recession, loss of market value, and deflation. Various financial crises at the turn of the 20th century, such as the Asian Crisis of 1997-1998 and the 2007-2008 Global Financial Crisis, have had immense impacts on the world economy. The COVID-19 pandemic also caused a financial crisis when mass lockdowns triggered staggering unemployment rates, a stagnation of economic growth, and led to the 2020 stock market crash. With the Russian invasion of Ukraine, the world has also witnessed a global energy crisis with shortages and increased prices in oil, gas, and electricity markets. According to UNCTAD’s World of Debt 2025, global public debt surpassed $100 trillion in 2024, with developing country debt growing twice as fast as developed economies since 2010. Burdens of debt servicing come with economic slowdowns and demands of austerity from lenders, with some economists arguing that this will lead to a new “lost decade” for the Global South. IPS brings you worldwide coverage of these financial developments and how we should manage these crises.

The Week with IPS

NEXT STOP - SDGs
Tracking global progress towards a sustainable world
Tracking global progress towards a sustainable world
